Kozi checks and balances
update

Kozi Checks & Balances
Media Site Home

cropper
update
  • Categories
    • Kansas Tax Compliance
    • Audit-Proofing Strategies
    • Bookkeeping Basics
    • QuickBooks Optimization
    • Industry Insights
    • Tax Deduction Deep-Dives
    • Local Business Spotlights
    • Payroll Taxes
    • Business Directory
cropper
update
 Kozi Checks & Balances TaxTactics News 
cropper
update
December 12.2025
2 Minutes Read

Navigating the Controversial QSBS Exclusion: Investment Strategies for Startups

Quite the Skewed Business Subsidy: QSBS Exclusion Is a Poor Way to Encourage Investment

Understanding the Qualified Small Business Stock (QSBS) Exclusion

In the evolving landscape of U.S. tax law, the Qualified Small Business Stock (QSBS) exclusion has emerged as both a boon and a burden. Under Section 1202 of the Internal Revenue Code, this provision theoretically allows investors to exclude significant portions—up to 100%—of their capital gains when selling stock from qualified small businesses. Initially designed to stimulate investment in burgeoning startups, it inadvertently favors certain industries and complicates investment decisions.

The Case Against QSBS: Why It’s Viewed as a Distorted Subsidy

The QSBS exclusion has been critiqued for introducing distortive effects on market decisions. By primarily benefiting those who can afford specialized legal advice, it skews investment toward particular structures and expansions that may not reflect genuine business fundamentals. For instance, provisions set out in the One Big Beautiful Bill Act (OBBBA) exacerbate these distortions with increased limits and eligibility criteria, leading to greater complexity while making it harder for average investors to engage effectively.

Alternatives to QSBS for Encouraging Investment

Many economists argue that simplifying tax codes to promote expensing of short-lived assets would better serve growth. A streamlined approach not only reduces complexity but ensures that investment decisions are based on business needs rather than tax incentives. OBBBA's other provisions, which improve capital investment treatment, take steps in this direction but still fall short of eliminating QSBS’s convoluted legacy.

Future Predictions: What Lies Ahead for QSBS Regulations

As we look forward, it's essential to monitor how the QSBS policies evolve and their long-term implications on investment behavior. With growing concerns about fairness and neutrality in tax codes, potential reforms may phase out or revise the QSBS exclusion to better reflect equitable economic practices. This could steer investments toward industries that truly need capital infusion rather than merely those that can navigate the complexities of the current system.

Common Misconceptions About QSBS

Amidst the complexities surrounding QSBS, several myths persist, particularly among new investors. One widespread belief is that all shares held in startup contexts qualify for the tax exclusion. However, this assumption can lead to unexpected tax liabilities for those unfamiliar with the intricate requirements governed by gross asset limits, duration of stock holding, and active business status.

Your Next Steps: Navigating the QSBS Landscape

For stakeholders in the startup ecosystem—founders, early employees, and even seasoned investors—familiarity with QSBS qualifications is vital. The potential for achieving significant tax savings by leveraging QSBS calls for strategic planning and awareness. For many, the best approach involves engaging experienced tax professionals who can aid in the nuances of the current tax environment, ensuring you can maximize your investment returns while adhering to evolving regulations.
Tax Deduction Deep-Dives

0 Comments

Write A Comment

*
*
Please complete the captcha to submit your comment.
Related Posts All Posts
10.17.2026

Spain's Recent Tax Reforms: A Competitive Edge for Regions

Update Spain's Fiscal Evolution: A Decade of Competition Over the last ten years, Spain's autonomous communities have seized the opportunity to reshape their tax systems, becoming increasingly competitive in attracting entrepreneurs and residents alike. According to the latest Regional Tax Competitiveness Index (RTCI), we now witness a notable divergence between regions that have embraced reform and those that have lagged behind. Regions like Extremadura and Andalusia have undergone remarkable transformations, reflecting broader trends in fiscal policy across the nation. Extremadura's Rise: From Laggard to Leader Extremadura stands out as a prime example of how strategic reforms can significantly elevate a region's tax appeal. With a comprehensive reform agenda that started in earnest around 2017, Extremadura improved its standing from 19th to 8th place in the RTCI. Key reforms included the introduction of a 99% inheritance tax rebate for close relatives and, notably, a wealth tax exemption approved in 2023. These efforts, combined with reductions in income tax rates for lower-income earners, have positioned Extremadura among Spain's most competitive regions. Andalusia's Comprehensive Tax Strategy Hot on Extremadura's heels is Andalusia, which has also witnessed significant improvements, climbing from the 16th to the 7th position over the decade. The region's strategy has included persistent reductions in personal income tax rates and the introduction of tax bracket indexation to combat inflation. By cutting inheritance tax rates by 99% and enhancing exemptions for close relatives, Andalusia solidified its market position. The changes across various tax categories—such as property transfer taxes—have been pivotal in transforming it into a more attractive place for both businesses and residents. Lessons from Spain's Tax Reforms The experiences of Extremadura and Andalusia offer essential lessons for other regions contemplating tax reform. By focusing on competitive tax structures and reducing the burden on individuals and families, regions can stimulate economic growth and enhance their appeal. As we approach 2026, the ongoing evolution of Spain’s tax landscape remains a critical area for businesses and policymakers alike. Understanding these shifts in the fiscal landscape is valuable for readers wanting to engage with Spain's economic dynamics. By analyzing how tax reform impacts regional competitiveness, one can better anticipate future trends in both local and national economies. It is crucial for potential investors, entrepreneurs, and residents to stay informed and consider how these developments may influence their financial strategies and decisions.

10.16.2026

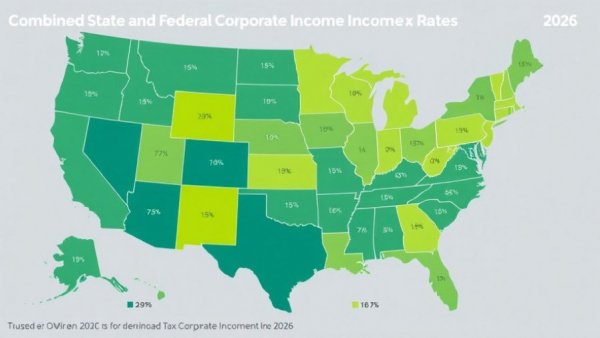
Understanding Combined State and Federal Corporate Tax Rates by 2026

Update The Landscape of Corporate Income Tax Rates in 2026As we approach 2026, understanding the combined state and federal corporate income tax rates becomes increasingly essential for businesses navigating the complex fiscal landscape. Currently, federal taxes on corporate income in the United States are set at a rate of 21%. However, corporations face a patchwork of additional state taxes, with top state rates ranging notably from 2% in North Carolina to a staggering 11.5% in New Jersey. Notably, New Jersey has the highest combined corporate income tax rate at a daunting 30.1%.Types of Corporate Taxes ImposedIn addition to corporate income taxes, states may impose various taxes that complicate the overall tax burden. Thirteen states employ graduated tax rates, while 31, along with Washington D.C., use a flat rate. Some states like Ohio and Texas opt for gross receipts taxes instead of traditional corporate income taxes, dramatically altering the financial landscape for local businesses. As such, understanding where a corporation operates is key to calculating its effective tax rate.Impact of State Taxes on Effective RatesThe actual tax burden on a corporation is not solely dictated by the headline rates but also incorporates adjustments, such as deductions. For instance, many states allow corporations to deduct some or all of their state corporate income taxes paid when calculating their federal taxable income. This mechanism can effectively lower corporate income rates even further, creating a disparity in effective rates faced by corporations across the U.S.Future Considerations and Economic ImpactLooking ahead, the way states manage corporate taxes is poised to significantly influence business decisions, impacting competitiveness within the U.S. economy. Reduced tax burdens or streamlined tax codes could serve as incentives for companies to relocate or expand operations in states with more favorable tax climates.Conclusion: Staying InformedFor businesses and stakeholders, it’s crucial to stay attuned to changes in tax policies that could affect operational costs and profitability. With significant variation across the states, proactive engagement with tax data can lead to informed decisions that enhance fiscal resilience.

10.16.2026

Corporate Income Tax Rates in 2026: What Every Business Needs to Know

Update Understanding Corporate Income Tax Structures in 2026 In 2026, corporations in the United States will face a comprehensive landscape of corporate income taxes at both federal and state levels. Currently, the federal corporate income tax sits at a rate of 21 percent. Adding to this, 44 states and the District of Columbia impose various taxes on corporate income, creating significant differences in overall tax burdens across the nation. State Variability: A Closer Look at Tax Rates The range of state-level corporate tax rates is striking, with figures ranging from just 2.0 percent in North Carolina to a steep 11.5 percent in New Jersey, making it the state with the highest combined rate at 30.1 percent. Meanwhile, six states—Ohio, Nevada, South Dakota, Texas, Washington, and Wyoming—have no corporate taxes at the state level, retaining only the federal tax burden. Among these, gross receipts taxes can create additional obligations for businesses. The Impact of Deductions on Tax Liabilities Tax deductions can significantly alter the effective tax rate for corporations. For states like Rhode Island, businesses can deduct state corporate taxes from their federal taxable income, effectively reducing the federal rate further. For example, a 7 percent state tax could lower the federal rate to about 19.53 percent, thereby bringing the combined effective tax rate down considerably. Furthermore, states like Alabama and Missouri allow corporations to deduct federal tax liabilities, significantly easing the overall tax burden. The Average Corporate Tax Rate in the U.S. When combining both federal and state corporate income taxes, the average corporate tax rate across the U.S. is projected to be around 25.5 percent. This statistic underscores the importance for corporations to navigate the intricate tax landscape thoughtfully and strategically, as high tax burdens can hinder business growth and competitiveness. Strategies for Corporations As companies face pressures to adapt to evolving economic conditions, understanding these tax policies is crucial. Optimizing tax liability can unlock significant financial resources for investment and growth. Moreover, corporations should stay informed about potential reforms that aim to simplify tax structures and enhance economic competitiveness, underscoring the symbiotic relationship between corporate taxes and business health.

cropper
update
Kozi Checks & Balances
Tax Tatics News
cropper
update

Tax optimization strategies and compliance guidance tailored for small businesses in Kansas. This includes actionable insights on state-specific tax laws, bookkeeping tips, compliance updates, and financial planning strategies to maximize savings and efficiency.

  • update
  • update
  • update
  • update
  • update
  • update
  • update
UPDATE

913-543-3903

AVAILABLE FROM Monday-Friday

Address

Kozi Checks & Balances
1300 N 78TH STREET
SUITE G05
KANSAS CITY, KS 66112-2406

ABOUT US

Tax Tactics News distinguishes itself with hyper-localized content specifically addressing Kansas’ unique tax environment. By focusing on small businesses, freelancers, and entrepreneurs, the platform serves as a trusted advisor for compliance and tax optimization, cutting through generic advice to offer precise, practical solutions and Referrals.

© 2026 Kozi Checks & Balances All Rights Reserved. 1300 N 78TH STREET, Suite GO5, Kansas CIty, Ks 66112 . Contact Us . Terms of Service . Privacy Policy

eyJjb21wYW55IjoiS296aSBDaGVja3MgJiBCYWxhbmNlcyIsImFkZHJlc3MiOiIxMzAwIE4gNzhUSCBTVFJFRVQsIFN1aXRlIEdPNSIsImNpdHkiOiJLYW5zYXMgQ0l0eSIsInN0YXRlIjoiS3MiLCJ6aXAiOiI2NjExMiIsImVtYWlsIjoibWlrZUBrb3ppY2hlY2tzLmNvbSIsInRvcyI6IlBIQStQSE4wY205dVp6NDhaVzArVjJobGJpQjViM1VnYzJsbmJpMXBiaUIzYVhSb0lIVnpMQ0I1YjNVZ1lYSmxJR2RwZG1sdVp5WnVZbk53T3lCNWIzVnlJSEJsY20xcGMzTnBiMjRnWVc1a0lHTnZibk5sYm5RZ2RHOGdjMlZ1WkNCNWIzVWdaVzFoYVd3Z1lXNWtMMjl5SUZOTlV5QjBaWGgwSUcxbGMzTmhaMlZ6TGlCQ2VTQmphR1ZqYTJsdVp5QjBhR1VnVkdWeWJYTWdZVzVrSUVOdmJtUnBkR2x2Ym5NZ1ltOTRJR0Z1WkNCaWVTQnphV2R1YVc1bklHbHVJSGx2ZFNCaGRYUnZiV0YwYVdOaGJHeDVJR052Ym1acGNtMGdkR2hoZENCNWIzVWdZV05qWlhCMElHRnNiQ0IwWlhKdGN5QnBiaUIwYUdseklHRm5jbVZsYldWdWRDNDhMMlZ0UGp3dmMzUnliMjVuUGp3dmNENEtDanh3UGp4aElHaHlaV1k5SW1oMGRIQTZMeTkzZDNjdVoyOXZaMnhsTG1OdmJTSSthSFIwY0RvdkwzZDNkeTVuYjI5bmJHVXVZMjl0UEM5aFBqd3ZjRDRLQ2p4d1BpWnVZbk53T3p3dmNENEtDanh3UGp4emRISnZibWMrVTBWU1ZrbERSVHd2YzNSeWIyNW5Qand2Y0Q0S0NqeHdQbGRsSUhCeWIzWnBaR1VnWVNCelpYSjJhV05sSUhSb1lYUWdZM1Z5Y21WdWRHeDVJR0ZzYkc5M2N5QjViM1VnZEc4Z2NtVmpaV2wyWlNCeVpYRjFaWE4wY3lCbWIzSWdabVZsWkdKaFkyc3NJR052YlhCaGJua2dhVzVtYjNKdFlYUnBiMjRzSUhCeWIyMXZkR2x2Ym1Gc0lHbHVabTl5YldGMGFXOXVMQ0JqYjIxd1lXNTVJR0ZzWlhKMGN5d2dZMjkxY0c5dWN5d2daR2x6WTI5MWJuUnpJR0Z1WkNCdmRHaGxjaUJ1YjNScFptbGpZWFJwYjI1eklIUnZJSGx2ZFhJZ1pXMWhhV3dnWVdSa2NtVnpjeUJoYm1RdmIzSWdZMlZzYkhWc1lYSWdjR2h2Ym1VZ2IzSWdaR1YyYVdObExpQlpiM1VnZFc1a1pYSnpkR0Z1WkNCaGJtUWdZV2R5WldVZ2RHaGhkQ0IwYUdVZ1UyVnlkbWxqWlNCcGN5QndjbTkyYVdSbFpDQW1jWFZ2ZER0QlV5MUpVeVp4ZFc5ME95QmhibVFnZEdoaGRDQjNaU0JoYzNOMWJXVWdibThnY21WemNHOXVjMmxpYVd4cGRIa2dabTl5SUhSb1pTQjBhVzFsYkdsdVpYTnpMQ0JrWld4bGRHbHZiaXdnYldsekxXUmxiR2wyWlhKNUlHOXlJR1poYVd4MWNtVWdkRzhnYzNSdmNtVWdZVzU1SUhWelpYSWdZMjl0YlhWdWFXTmhkR2x2Ym5NZ2IzSWdjR1Z5YzI5dVlXeHBlbUYwYVc5dUlITmxkSFJwYm1kekxqd3ZjRDRLQ2p4d1BsbHZkU0JoY21VZ2NtVnpjRzl1YzJsaWJHVWdabTl5SUc5aWRHRnBibWx1WnlCaFkyTmxjM01nZEc4Z2RHaGxJRk5sY25acFkyVWdZVzVrSUhSb1lYUWdZV05qWlhOeklHMWhlU0JwYm5admJIWmxJSFJvYVhKa0lIQmhjblI1SUdabFpYTWdLSE4xWTJnZ1lYTWdVMDFUSUhSbGVIUWdiV1Z6YzJGblpYTXNJRWx1ZEdWeWJtVjBJSE5sY25acFkyVWdjSEp2ZG1sa1pYSWdiM0lnWTJWc2JIVnNZWElnWVdseWRHbHRaU0JqYUdGeVoyVnpLUzRnV1c5MUlHRnlaU0J5WlhOd2IyNXphV0pzWlNCbWIzSWdkR2h2YzJVZ1ptVmxjeXdnYVc1amJIVmthVzVuSUhSb2IzTmxJR1psWlhNZ1lYTnpiMk5wWVhSbFpDQjNhWFJvSUhSb1pTQmthWE53YkdGNUlHOXlJR1JsYkdsMlpYSjVJRzltSUdWaFkyZ2dVMDFUSUhSbGVIUWdiV1Z6YzJGblpTQnpaVzUwSUhSdklIbHZkU0JpZVNCMWN5NGdTVzRnWVdSa2FYUnBiMjRzSUhsdmRTQnRkWE4wSUhCeWIzWnBaR1VnWVc1a0lHRnlaU0J5WlhOd2IyNXphV0pzWlNCbWIzSWdZV3hzSUdWeGRXbHdiV1Z1ZENCdVpXTmxjM05oY25rZ2RHOGdZV05qWlhOeklIUm9aU0JUWlhKMmFXTmxJR0Z1WkNCeVpXTmxhWFpsSUhSb1pTQlRUVk1nZEdWNGRDQnRaWE56WVdkbGN5NGdWMlVnWkc4Z2JtOTBJR05vWVhKblpTQmhibmtnWm1WbGN5Qm1iM0lnWkdWc2FYWmxjbmtnYjJZZ1pXMWhhV3dnYjNJZ1UwMVRMaUJVYUdseklHbHpJR0VnWm5KbFpTQnpaWEoyYVdObElIQnliM1pwWkdWa0lHSjVJSFZ6TGlCSWIzZGxkbVZ5TENCd2JHVmhjMlVnWTJobFkyc2dkMmwwYUNCNWIzVnlJR2x1ZEdWeWJtVjBJSE5sY25acFkyVWdjSEp2ZG1sa1pYSWdZVzVrSUdObGJHeDFiR0Z5SUdOaGNuSnBaWElnWm05eUlHRnVlU0JqYUdGeVoyVnpJSFJvWVhRZ2JXRjVJR2x1WTNWeUlHRnpJR0VnY21WemRXeDBJR1p5YjIwZ2NtVmpaV2wyYVc1bklHVnRZV2xzSUdGdVpDQlRUVk1nZEdWNGRDQnRaWE56WVdkbGN5QjBhR0YwSUhkbElHUmxiR2wyWlhJZ2RYQnZiaUI1YjNWeUlHOXdkQzFwYmlCaGJtUWdjbVZuYVhOMGNtRjBhVzl1SUhkcGRHZ2diM1Z5SUdWdFlXbHNJR0Z1WkNCVFRWTWdjMlZ5ZG1salpYTXVJRmx2ZFNCallXNGdZMkZ1WTJWc0lHRjBJR0Z1ZVNCMGFXMWxMaUJLZFhOMElIUmxlSFFnSm5GMWIzUTdVMVJQVUNaeGRXOTBPeUIwYnladVluTndPenhvYVdkb2JHbG5hSFFnWTJ4aGMzTTlJbU52YlhCaGJubFRUVk5RYUc5dVpWVndaR0YwWlNJK0tEa3hNeWtnTlRRekxUTTVNRE04TDJocFoyaHNhV2RvZEQ0dUlFRm1kR1Z5SUhsdmRTQnpaVzVrSUhSb1pTQlRUVk1nYldWemMyRm5aU0FtY1hWdmREdFRWRTlRSm5GMWIzUTdJSFJ2SUhWekxDQjNaU0IzYVd4c0lITmxibVFnZVc5MUlHRnVJRk5OVXlCdFpYTnpZV2RsSUhSdklHTnZibVpwY20wZ2RHaGhkQ0I1YjNVZ2FHRjJaU0JpWldWdUlIVnVjM1ZpYzJOeWFXSmxaQzRnUVdaMFpYSWdkR2hwY3l3Z2VXOTFJSGRwYkd3Z2JtOGdiRzl1WjJWeUlISmxZMlZwZG1VZ1UwMVRJRzFsYzNOaFoyVnpJR1p5YjIwZ2RYTXVQQzl3UGdvS1BIQStQSE4wY205dVp6NVpUMVZTSUZKRlIwbFRWRkpCVkVsUFRpQlBRa3hKUjBGVVNVOU9Vend2YzNSeWIyNW5Qand2Y0Q0S0NqeHdQa2x1SUdOdmJuTnBaR1Z5WVhScGIyNGdiMllnZVc5MWNpQjFjMlVnYjJZZ2RHaGxJRk5sY25acFkyVXNJSGx2ZFNCaFozSmxaU0IwYnpvOEwzQStDZ284YjJ3K0NnazhiR2srY0hKdmRtbGtaU0IwY25WbExDQmhZMk4xY21GMFpTd2dZM1Z5Y21WdWRDQmhibVFnWTI5dGNHeGxkR1VnYVc1bWIzSnRZWFJwYjI0Z1lXSnZkWFFnZVc5MWNuTmxiR1lnWVhNZ2NISnZiWEIwWldRZ1lua2dkR2hsSUZObGNuWnBZMlVtSXpNNU8zTWdjbVZuYVhOMGNtRjBhVzl1SUdadmNtMGdLSE4xWTJnZ2FXNW1iM0p0WVhScGIyNGdZbVZwYm1jZ2RHaGxJQ1p4ZFc5ME8xSmxaMmx6ZEhKaGRHbHZiaUJFWVhSaEpuRjFiM1E3S1NCaGJtUThMMnhwUGdvSlBHeHBQbTFoYVc1MFlXbHVJR0Z1WkNCd2NtOXRjSFJzZVNCMWNHUmhkR1VnZEdobElGSmxaMmx6ZEhKaGRHbHZiaUJFWVhSaElIUnZJR3RsWlhBZ2FYUWdkSEoxWlN3Z1lXTmpkWEpoZEdVc0lHTjFjbkpsYm5RZ1lXNWtJR052YlhCc1pYUmxMaUJKWmlCNWIzVWdjSEp2ZG1sa1pTQmhibmtnYVc1bWIzSnRZWFJwYjI0Z2RHaGhkQ0JwY3lCMWJuUnlkV1VzSUdsdVlXTmpkWEpoZEdVc0lHNXZkQ0JqZFhKeVpXNTBJRzl5SUdsdVkyOXRjR3hsZEdVc0lHOXlJSGRsSUdoaGRtVWdjbVZoYzI5dVlXSnNaU0JuY205MWJtUnpJSFJ2SUhOMWMzQmxZM1FnZEdoaGRDQnpkV05vSUdsdVptOXliV0YwYVc5dUlHbHpJSFZ1ZEhKMVpTd2dhVzVoWTJOMWNtRjBaU3dnYm05MElHTjFjbkpsYm5RZ2IzSWdhVzVqYjIxd2JHVjBaU3dnZDJVZ2FHRjJaU0IwYUdVZ2NtbG5hSFFnZEc4Z2MzVnpjR1Z1WkNCdmNpQThjM1J5YjI1blBqeHpjR0Z1SUhOMGVXeGxQU0pqYjJ4dmNqb2pSa1l3TURBd095SStkR1Z5YldsdVlYUmxJSGx2ZFhJZ1lXTmpiM1Z1ZEM5d2NtOW1hV3hsSUdGdVpDQnlaV1oxYzJVZ1lXNTVJR0Z1WkNCaGJHd2dZM1Z5Y21WdWRDQnZjaUJtZFhSMWNtVWdkWE5sSUc5bUlIUm9aU0JUWlhKMmFXTmxJQ2h2Y2lCaGJua2djRzl5ZEdsdmJpQjBhR1Z5Wlc5bUtTNDhMM053WVc0K1BDOXpkSEp2Ym1jK1BDOXNhVDRLUEM5dmJENEtDanh3UGladVluTndPend2Y0Q0S1BHaHBaMmhzYVdkb2RDQmpiR0Z6Y3owaVkyOXRjR0Z1ZVU1aGJXVlZjR1JoZEdVaVBrdHZlbWtnUTJobFkydHpJQ1poYlhBN0lFSmhiR0Z1WTJWelBDOW9hV2RvYkdsbmFIUStQR0p5SUM4K0NqeG9hV2RvYkdsbmFIUWdZMnhoYzNNOUltTnZiWEJoYm5sQlpHUnlaWE56VlhCa1lYUmxJajR4TXpBd0lFNGdOemhVU0NCVFZGSkZSVlFzSUZOMWFYUmxJRWRQTlN3Z1MyRnVjMkZ6SUVOSmRIa3NJRXR6SURZMk1URXlQQzlvYVdkb2JHbG5hSFErUEdKeUlDOCtDanhvYVdkb2JHbG5hSFFnWTJ4aGMzTTlJbU52YlhCaGJubFFhRzl1WlZWd1pHRjBaU0krS3pFZ0t6RTVNVE0xTkRNek9UQXpQQzlvYVdkb2JHbG5hSFErUEdKeUlDOCtDanhvYVdkb2JHbG5hSFFnWTJ4aGMzTTlJbU52YlhCaGJubEZiV0ZwYkZWd1pHRjBaU0krYldsclpVQnJiM3BwWTJobFkydHpMbU52YlR3dmFHbG5hR3hwWjJoMFBnPT0iLCJwcml2YWN5IjoiUEhBK1BITjBjbTl1Wno1UVVrbFdRVU5aUEM5emRISnZibWMrUEM5d1Bnb0tQSEErUEhOMGNtOXVaejVVYUdVZ2FXNW1iM0p0WVhScGIyNGdjSEp2ZG1sa1pXUWdaSFZ5YVc1bklIUm9hWE1nY21WbmFYTjBjbUYwYVc5dUlHbHpJR3RsY0hRZ2NISnBkbUYwWlNCaGJtUWdZMjl1Wm1sa1pXNTBhV0ZzTENCaGJtUWdkMmxzYkNCdVpYWmxjaUJpWlNCa2FYTjBjbWxpZFhSbFpDd2dZMjl3YVdWa0xDQnpiMnhrTENCMGNtRmtaV1FnYjNJZ2NHOXpkR1ZrSUdsdUlHRnVlU0IzWVhrc0lITm9ZWEJsSUc5eUlHWnZjbTB1SUZSb2FYTWdhWE1nYjNWeUlHZDFZWEpoYm5SbFpTNDhMM04wY205dVp6NDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrbE9SRVZOVGtsVVdUd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4d1BqeGxiVDVaYjNVZ1lXZHlaV1VnZEc4Z2FXNWtaVzF1YVdaNUlHRnVaQ0JvYjJ4a0lIVnpMQzRnWVc1a0lHbDBjeUJ6ZFdKemFXUnBZWEpwWlhNc0lHRm1abWxzYVdGMFpYTXNJRzltWm1salpYSnpMQ0JoWjJWdWRITXNJR052TFdKeVlXNWtaWEp6SUc5eUlHOTBhR1Z5SUhCaGNuUnVaWEp6TENCaGJtUWdaVzF3Ykc5NVpXVnpMQ0JvWVhKdGJHVnpjeUJtY205dElHRnVlU0JqYkdGcGJTQnZjaUJrWlcxaGJtUXNJR2x1WTJ4MVpHbHVaeUJ5WldGemIyNWhZbXhsSUdGMGRHOXlibVY1Y3lZak16azdJR1psWlhNc0lHMWhaR1VnWW5rZ1lXNTVJSFJvYVhKa0lIQmhjblI1SUdSMVpTQjBieUJ2Y2lCaGNtbHphVzVuSUc5MWRDQnZaaUJEYjI1MFpXNTBJSGx2ZFNCeVpXTmxhWFpsTENCemRXSnRhWFFzSUhKbGNHeDVMQ0J3YjNOMExDQjBjbUZ1YzIxcGRDQnZjaUJ0WVd0bElHRjJZV2xzWVdKc1pTQjBhSEp2ZFdkb0lIUm9aU0JUWlhKMmFXTmxMQ0I1YjNWeUlIVnpaU0J2WmlCMGFHVWdVMlZ5ZG1salpTd2dlVzkxY2lCamIyNXVaV04wYVc5dUlIUnZJSFJvWlNCVFpYSjJhV05sTENCNWIzVnlJSFpwYjJ4aGRHbHZiaUJ2WmlCMGFHVWdWRTlUTENCdmNpQjViM1Z5SUhacGIyeGhkR2x2YmlCdlppQmhibmtnY21sbmFIUnpJRzltSUdGdWIzUm9aWEl1UEM5bGJUNDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrUkpVME5NUVVsTlJWSWdUMFlnVjBGU1VrRk9WRWxGVXp3dmMzUnliMjVuUGp3dmNENEtDanh3UGp4emRISnZibWMrV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVU9qd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4dmJENEtDVHhzYVQ1WlQxVlNJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCQlZDQlpUMVZTSUZOUFRFVWdVa2xUU3k0Z1ZFaEZJRk5GVWxaSlEwVWdTVk1nVUZKUFZrbEVSVVFnVDA0Z1FVNGdKbkYxYjNRN1FWTWdTVk1tY1hWdmREc2dRVTVFSUNaeGRXOTBPMEZUSUVGV1FVbE1RVUpNUlNaeGRXOTBPeUJDUVZOSlV5NGdMQzRnUVU1RUlGVlRMQ0JKVkNZak16azdVeUJEVlZOVVQwMUZVbE1zSUVWWVVGSkZVMU5NV1NCRVNWTkRURUZKVFZNZ1FVeE1JRmRCVWxKQlRsUkpSVk1nVDBZZ1FVNVpJRXRKVGtRc0lGZElSVlJJUlZJZ1JWaFFVa1ZUVXlCUFVpQkpUVkJNU1VWRUxDQkpUa05NVlVSSlRrY3NJRUpWVkNCT1QxUWdURWxOU1ZSRlJDQlVUeUJVU0VVZ1NVMVFURWxGUkNCWFFWSlNRVTVVU1VWVElFOUdJRTFGVWtOSVFVNVVRVUpKVEVsVVdTd2dSa2xVVGtWVFV5QkdUMUlnUVNCUVFWSlVTVU5WVEVGU0lGQlZVbEJQVTBVZ1FVNUVJRTVQVGkxSlRrWlNTVTVIUlUxRlRsUXVQQzlzYVQ0S0NUeHNhVDVOUVV0RlV5Qk9UeUJYUVZKU1FVNVVXU0JVU0VGVUlDaHBLU0JVU0VVZ1UwVlNWa2xEUlNCWFNVeE1JRTFGUlZRZ1dVOVZVaUJTUlZGVlNWSkZUVVZPVkZNc0lDaHBhU2tnVkVoRklGTkZVbFpKUTBVZ1YwbE1UQ0JDUlNCVlRrbE9WRVZTVWxWUVZFVkVMQ0JVU1UxRlRGa3NJRk5GUTFWU1JTd2dUMUlnUlZKU1QxSXRSbEpGUlN3Z0tHbHBhU2tnVkVoRklGSkZVMVZNVkZNZ1ZFaEJWQ0JOUVZrZ1FrVWdUMEpVUVVsT1JVUWdSbEpQVFNCVVNFVWdWVk5GSUU5R0lGUklSU0JUUlZKV1NVTkZJRmRKVEV3Z1FrVWdRVU5EVlZKQlZFVWdUMUlnVWtWTVNVRkNURVVzSUVGT1JDQW9hWFlwSUVGT1dTQkZVbEpQVWxNZ1NVNGdWRWhGSUZOUFJsUlhRVkpGSUZkSlRFd2dRa1VnUTA5U1VrVkRWRVZFTGp3dmJHaytDZ2s4YkdrK1FVNVpJRTFCVkVWU1NVRk1JRVJQVjA1TVQwRkVSVVFnVDFJZ1QxUklSVkpYU1ZORklFOUNWRUZKVGtWRUlGUklVazlWUjBnZ1ZFaEZJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCRVQwNUZJRUZVSUZsUFZWSWdUMWRPSUVSSlUwTlNSVlJKVDA0Z1FVNUVJRkpKVTBzZ1FVNUVJRlJJUVZRZ1dVOVZJRmRKVEV3Z1FrVWdVMDlNUlV4WklGSkZVMUJQVGxOSlFreEZJRVpQVWlCQlRsa2dSRUZOUVVkRklGUlBJRmxQVlZJZ1EwOU5VRlZVUlZJZ1UxbFRWRVZOSUU5U0lFeFBVMU1nVDBZZ1JFRlVRU0JVU0VGVUlGSkZVMVZNVkZNZ1JsSlBUU0JVU0VVZ1JFOVhUa3hQUVVRZ1QwWWdRVTVaSUZOVlEwZ2dUVUZVUlZKSlFVd3VQQzlzYVQ0S0NUeHNhVDVPVHlCQlJGWkpRMFVnVDFJZ1NVNUdUMUpOUVZSSlQwNHNJRmRJUlZSSVJWSWdUMUpCVENCUFVpQlhVa2xVVkVWT0xDQlBRbFJCU1U1RlJDQkNXU0JaVDFVZ1JsSlBUU0JQVWlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVZ1UwaEJURXdnUTFKRlFWUkZJRUZPV1NCWFFWSlNRVTVVV1NCT1QxUWdSVmhRVWtWVFUweFpJRk5VUVZSRlJDQkpUaUJVU0VVZ1ZFOVRMand2YkdrK0Nqd3ZiMncrQ2dvOGNENDhjM1J5YjI1blBreEpUVWxVUVZSSlQwNGdUMFlnVEVsQlFrbE1TVlJaUEM5emRISnZibWMrUEM5d1Bnb0tQSEErV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVUlFRk9SQ0JUU0VGTVRDQk9UMVFnUWtVZ1RFbEJRa3hGSUVaUFVpQkJUbGtnUkVsU1JVTlVMQ0JKVGtSSlVrVkRWQ3dnU1U1RFNVUkZUbFJCVEN3Z1UxQkZRMGxCVEN3Z1EwOU9VMFZSVlVWT1ZFbEJUQ0JQVWlCRldFVk5VRXhCVWxrZ1JFRk5RVWRGVXl3Z1NVNURURlZFU1U1SElFSlZWQ0JPVDFRZ1RFbE5TVlJGUkNCVVR5d2dSRUZOUVVkRlV5QkdUMUlnVEU5VFV5QlBSaUJRVWs5R1NWUlRMQ0JIVDA5RVYwbE1UQ3dnVlZORkxDQkVRVlJCSUU5U0lFOVVTRVZTSUVsT1ZFRk9SMGxDVEVVZ1RFOVRVMFZUSUNoRlZrVk9JRWxHSUVoQlV5QkNSVVZPSUVGRVZrbFRSVVFnVDBZZ1ZFaEZJRkJQVTFOSlFrbE1TVlJaSUU5R0lGTlZRMGdnUkVGTlFVZEZVeWtzSUZKRlUxVk1WRWxPUnlCR1VrOU5Pand2Y0Q0S0NqeHZiRDRLQ1R4c2FUNVVTRVVnVlZORklFOVNJRlJJUlNCSlRrRkNTVXhKVkZrZ1ZFOGdWVk5GSUZSSVJTQlRSVkpXU1VORk96d3ZiR2srQ2drOGJHaytWRWhGSUVOUFUxUWdUMFlnVUZKUFExVlNSVTFGVGxRZ1QwWWdVMVZDVTFSSlZGVlVSU0JIVDA5RVV5QkJUa1FnVTBWU1ZrbERSVk1nVWtWVFZVeFVTVTVISUVaU1QwMGdRVTVaSUVkUFQwUlRMQ0JFUVZSQkxDQkpUa1pQVWsxQlZFbFBUaUJQVWlCVFJWSldTVU5GVXlCUVZWSkRTRUZUUlVRZ1QxSWdUMEpVUVVsT1JVUWdUMUlnVFVWVFUwRkhSVk1nVWtWRFJVbFdSVVFnVDFJZ1ZGSkJUbE5CUTFSSlQwNVRJRVZPVkVWU1JVUWdTVTVVVHlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVN1BDOXNhVDRLQ1R4c2FUNVZUa0ZWVkVoUFVrbGFSVVFnUVVORFJWTlRJRlJQSUU5U0lFRk1WRVZTUVZSSlQwNGdUMFlnV1U5VlVpQlVVa0ZPVTAxSlUxTkpUMDVUSUU5U0lFUkJWRUU3UEM5c2FUNEtDVHhzYVQ1VFZFRlVSVTFGVGxSVElFOVNJRU5QVGtSVlExUWdUMFlnUVU1WklGUklTVkpFSUZCQlVsUlpJRTlPSUZSSVJTQlRSVkpXU1VORk95QlBVand2YkdrK0NnazhiR2srUVU1WklFOVVTRVZTSUUxQlZGUkZVaUJTUlV4QlZFbE9SeUJVVHlCVVNFVWdVMFZTVmtsRFJTNDhMMnhwUGdvOEwyOXNQZ29LUEhBK1BIVStRbmtnY21WbmFYTjBaWEpwYm1jZ1lXNWtJSE4xWW5OamNtbGlhVzVuSUhSdklHOTFjaUJsYldGcGJDQmhibVFnVTAxVElITmxjblpwWTJVc0lHSjVJRzl3ZEMxcGJpd2diMjVzYVc1bElISmxaMmx6ZEhKaGRHbHZiaUJ2Y2lCaWVTQm1hV3hzYVc1bklHOTFkQ0JoSUdOaGNtUXNJQ1p4ZFc5ME8zbHZkU0JoWjNKbFpTQjBieUIwYUdWelpTQlVSVkpOVXlCUFJpQlRSVkpXU1VORkpuRjFiM1E3SUdGdVpDQjViM1VnWVdOcmJtOTNiR1ZrWjJVZ1lXNWtJSFZ1WkdWeWMzUmhibVFnZEdobElHRmliM1psSUhSbGNtMXpJRzltSUhObGNuWnBZMlVnYjNWMGJHbHVaV1FnWVc1a0lHUmxkR0ZwYkdWa0lHWnZjaUI1YjNVZ2RHOWtZWGt1UEM5MVBqd3ZjRDRLQ2p4d1BpWnVZbk53T3p3dmNENEtQR2hwWjJoc2FXZG9kQ0JqYkdGemN6MGlZMjl0Y0dGdWVVNWhiV1ZWY0dSaGRHVWlQa3R2ZW1rZ1EyaGxZMnR6SUNaaGJYQTdJRUpoYkdGdVkyVnpQQzlvYVdkb2JHbG5hSFErUEdKeUlDOCtDanhvYVdkb2JHbG5hSFFnWTJ4aGMzTTlJbU52YlhCaGJubEJaR1J5WlhOelZYQmtZWFJsSWo0eE16QXdJRTRnTnpoVVNDQlRWRkpGUlZRc0lGTjFhWFJsSUVkUE5Td2dTMkZ1YzJGeklFTkpkSGtzSUV0eklEWTJNVEV5UEM5b2FXZG9iR2xuYUhRK1BHSnlJQzgrQ2p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxRYUc5dVpWVndaR0YwWlNJK0t6RWdLekU1TVRNMU5ETXpPVEF6UEM5b2FXZG9iR2xuYUhRK1BHSnlJQzgrQ2p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxGYldGcGJGVndaR0YwWlNJK2JXbHJaVUJyYjNwcFkyaGxZMnR6TG1OdmJUd3ZhR2xuYUd4cFoyaDBQZz09In0=

Terms of Service

Privacy Policy

Core Modal Title

Sorry, no results found

You Might Find These Articles Interesting

T
Please Check Your Email
We Will Be Following Up Shortly
*
*
*